Categories
Home Buying TipsPublished November 11, 2026
First-Time Home Buyer Programs in the State of Delaware
Executive Summary
Delaware's first-time buyer program is Welcome Home, part of the statewide Delaware Mortgage Program run by Housing Delaware (formerly DSHA). It offers down payment and closing cost help worth 3%, 4% or 5% of your loan amount as a zero-interest second mortgage with no monthly payment. It isn't forgivable, so you repay it when you sell, refinance, transfer the title or move out. Each step up in assistance also raises your interest rate for the life of the loan. You need a 620 credit score, income and price under county limits, and a participating lender. In our experience it makes the most sense under $400,000, for buyers who really need the help and are buying their forever home.
Are you buying your first home in Delaware and wondering how much help with your down payment is really out there? And have you heard about the 3%, 4%, and 5% options, but can't get a straight answer on the catch, like whether you have to pay it back or what it does to your mortgage?
By the end of this article, you'll know exactly how Delaware's first-time buyer assistance works, what each option really costs you every month, and whether it makes sense for your plans.
We'll walk through the Welcome Home options, show real numbers from a lender comparison, cover who qualifies and the price range where the program works best, and lay out what to do before you make an offer.
What First-Time Home Buyer Programs Are Available in Delaware?
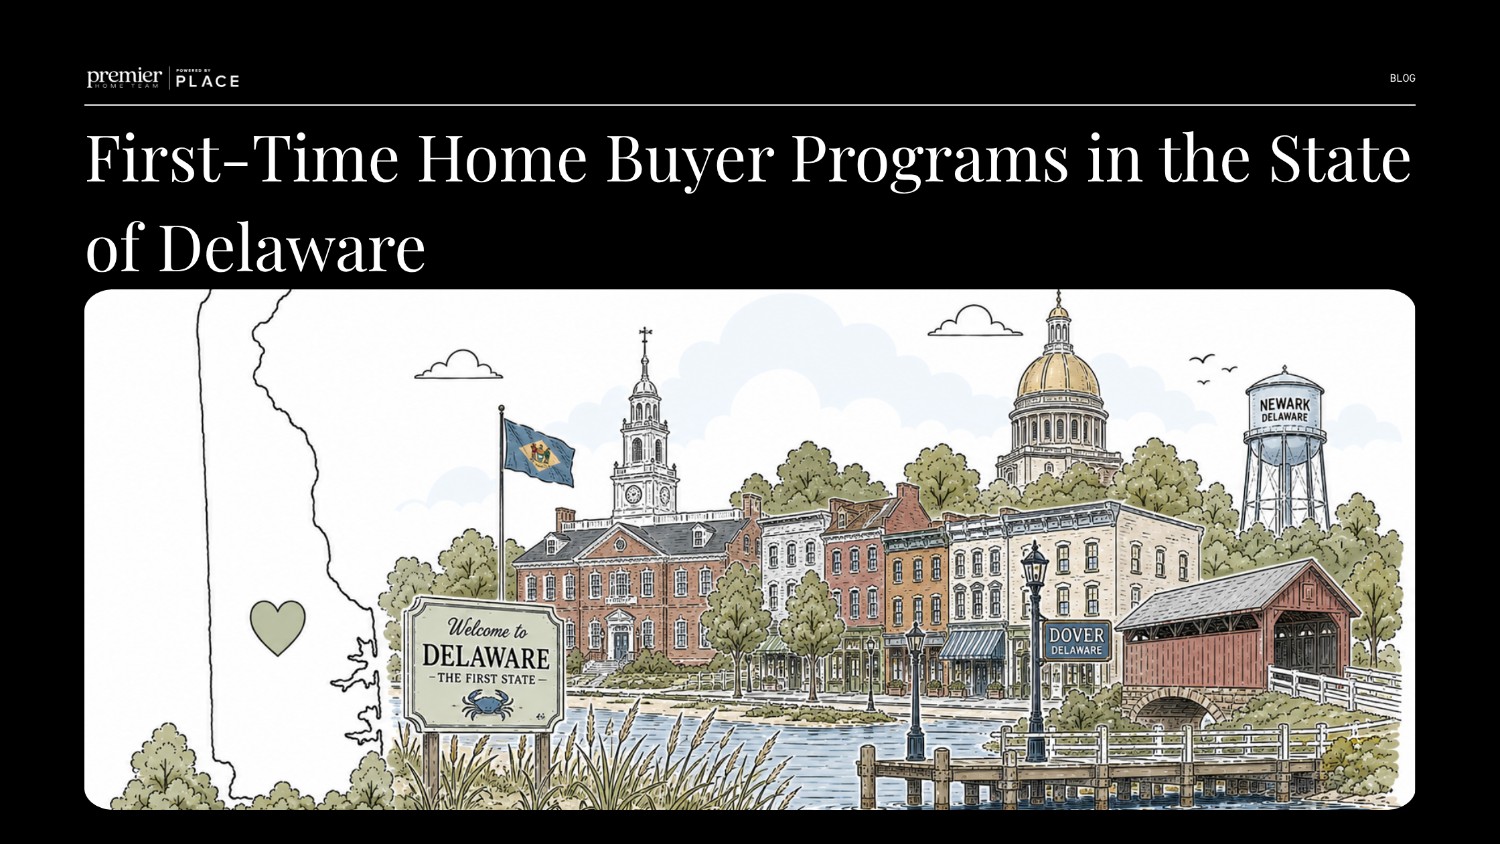
Unlike Pennsylvania, where assistance is mostly run county by county, Delaware has one statewide program. In April 2026, DSHA rebranded its single-family lending as the Delaware Mortgage Program, replacing the old "Kiss Your Landlord Goodbye" campaign. The agency itself now goes by Housing Delaware, though it still operates legally as DSHA, so you'll see both names.
The program has two tracks. Welcome Home is for first-time buyers. Open Door is for first-time and repeat buyers. Welcome Home has lower rates and the most assistance options, so it's usually where first-time buyers start.
Within Welcome Home, you pick one of these options:
| Option | Assistance | Interest on assistance | Monthly payment on assistance | Available through |
|---|---|---|---|---|
| Smart Start | None (first mortgage only) | N/A | N/A | Welcome Home and Open Door |
| First State | 3% of loan amount | 0% | None | Welcome Home and Open Door |
| Keys4You | 4% of loan amount | 0% | None | Welcome Home and Open Door |
| Take5 | 5% of loan amount | 0% | None | Welcome Home only |
| Diamond in the Rough | 5% of loan amount | 0% | None | Welcome Home only, for homes that need minor repairs (must qualify for FHA 203(k) limited) |
Source: Housing Delaware, Homeownership Loans, accessed October 19, 2026.
Most buyers don't realize Delaware's programs are orchestrated through the lender, so you'll need to choose one from Housing Delaware's participating lender list. Plenty of banks are on it, but some smaller lenders aren't, and they can't do the programs.
Is Delaware's Assistance a Grant or a Loan?
Delaware's assistance is a second mortgage that sits on top of your first one, similar to the Pennsylvania programs. It's zero interest, and there's no monthly payment, but it isn't forgivable. Housing Delaware requires you to pay it back when you sell, refinance or transfer the title, or when the home is no longer your primary residence, whichever comes first.
That's a very important detail, especially if this isn't your forever home. Whether you sell in two years or ten, or you refinance, the assistance is due. We lean on the lender to explain the ins and outs, since they're the ones facilitating it, and that's a big reason we point buyers to lenders we know will fully explain the programs. We still follow up afterward to make sure the terms are clear, because we don't want anyone caught off guard when they sell or refinance later.
When a buyer decided against it
We had a buyer who wanted to use the program, but once they found out it's not forgivable, they opted not to, because they didn't know if this would be their forever home. Instead, we asked for seller assistance and were able to get some. That kept their interest rate and payment down, and they don't have the assistance hanging over their head. If they want to sell in two years, five years or ten, it doesn't matter.
In our opinion, if it is your forever home, the program is probably a good option for you. If it's not, it really may not be the best option.
If you've looked at first-time buyer programs in Pennsylvania, Delaware's work differently. Some Pennsylvania programs are forgivable, which means you don't have to pay the money back as long as you stay in the home long enough. PHFA's Keystone Forgivable in Ten Years (K-FIT) loan is forgiven over 10 years, and Delaware County's Homeownership First program offers up to $10,000 as a deferred loan that's fully forgiven after five years if the home is in a designated Revitalization Area. If that's what you're used to, you might expect Delaware's assistance to work the same way, but it doesn't. The percentages may be around the same, but the terms behind the money are not. Our guide to what most buyers misunderstand about down payment assistance breaks down how grants, forgivable loans and deferred loans differ.
How Much Help Can a First-Time Buyer Get in Delaware?
Whether you take 3%, 4%, or 5% really depends on you, because as you go up in percentage, you do get more money, but your interest rate and your monthly payment go up too.
Here's a real comparison a participating lender ran for one of our clients in October 2026. It's an FHA 30-year fixed loan on a $285,000 home, with $9,975 down and a $279,838 loan amount, which includes FHA's upfront mortgage insurance.
| Option | Rate | Assistance | Cash due at closing | Principal & interest | Total monthly payment |
|---|---|---|---|---|---|
| First State (3%) | 7.00% | $8,550 | $14,476 | $1,862 | $2,381 |
| Keys4You (4%) | 7.50% | $11,440 | $11,597 | $1,957 | $2,476 |
| Take5 (5%) | 8.00% | $14,250 | $8,799 | $2,053 | $2,572 |
Total monthly payment includes about $200 in property taxes, $125 in homeowners insurance and $194 in FHA mortgage insurance. Rates change regularly, so check the current ones on Housing Delaware's rate page.
A whole point, like 7% versus 8%, definitely does make a difference. In this example, Take5 cuts what you bring to closing by about $5,700 compared with First State, but costs about $191 more every month, and you still repay the $14,250 when you sell or refinance.
If you really want your monthly payment to stay at a certain number, it's better to take less assistance. At the end of the day, the assistance is going to help you purchase, but that monthly payment is for 30 years, so you have to make that decision now. If you really need a lot more help with your closing costs, then taking more money is the smarter choice. But if you can, take the lesser amount, because it keeps both your interest rate and your monthly payment down.
Who Qualifies for First-Time Home Buyer Programs in Delaware?
According to Housing Delaware, to use Welcome Home, you need to:
- Be a first-time homebuyer, meaning you haven't owned a home in the past three years.
- Have a credit score of at least 620 (buyers at 680 or below must complete housing counseling)
- Fall under the income and purchase price limits for your county.
- Use a participating lender and live in the home as your primary residence.
A lender we work with on these loans told us he has never seen anyone approved below 620, and that buyers with credit scores below 680 take an online homebuyer class. You can use the program with a conventional, FHA, VA or USDA loan.
| County | Max income, 1 to 2 people | Max income, 3+ people | Max purchase price |
|---|---|---|---|
| New Castle | $122,700 | $141,105 | $659,385 |
| Kent and Sussex | $111,400 | $128,110 | $566,354 |
Welcome Home limits from Housing Delaware, accessed October 19, 2026. Higher limits and lower rates apply to homes in designated targeted areas, which your lender can check by address.
The official limits go higher, but in our opinion, the program works best from about $175,000 to $400,000. Above that, most buyers already have the money for closing costs, so taking assistance that raises their rate and isn't forgivable usually isn't in their best interest. If it were forgiven after 10 years, it would make sense. We always let buyers know the program is available, and the decision is always theirs. Our job is to make sure they understand the terms before they choose.
What Delaware First-Time Buyers Need to Do Before Making Offers
Start as early as possible. Everything needs to be in place before you go under contract.
- Tell your agent you want assistance. We usually bring it up at the buyer consultation.
- Talk to a participating lender. We'll connect you with three lenders who have facilitated the program for our clients. Choose the one you feel is best for you.
- Let the lender run your credit. You'll know right away whether you're approved, and if you qualify, you qualify for every percentage.
- Ask the right questions. Do you do the Delaware Mortgage Program? With my income and credit, do I qualify? Is the home in a targeted area with extra benefits?
- Choose your level of assistance. It comes down to how much financial risk you want to take.
No matter which participating lender you use, the program's interest rates are the same. We actually tested this recently, and both lenders came up with the same numbers. The lenders' own fees are a different story, so compare those. And if you specifically want this program and your lender doesn't do it, the only option is to switch lenders.
Can You Compete in Delaware's Market Using Assistance?
In our experience, it hasn't been a problem. The lender hasn't needed extra time for the program, and we haven't had a negative reaction from sellers because buyers using it usually aren't asking the seller for assistance. That said, Delaware is super competitive, and a lot of buyers don't want to put assistance in their offer at all. Our price points in Delaware have also often been higher, so some buyers didn't qualify. That's a big part of why only a handful of our buyers have used it so far, though with the market changing a little in some areas, we expect to help more.
Frequently Asked Questions
Are there first-time home buyer grants in Delaware?
Not through the Delaware Mortgage Program. Every assistance option is a zero-interest second mortgage that's never forgiven.
What credit score do I need?
At least 620. At 659 or below, you'll also complete free housing counseling through a HUD-approved counselor.
Can I use the program if I've owned a home before?
Not Welcome Home, unless you meet the first-time buyer definition. Open Door serves repeat buyers, with higher rates and up to 4% assistance.
Should I take the most assistance available?
If you don't need it, you probably don't want to do it. If you do, take as little as you can, since each step up raises your rate for the life of the loan.
Your Next Step as a Delaware Buyer
You came here wondering what help is available for your first Delaware home. The biggest thing to understand is the terms behind it. The help is a loan; it comes due when you sell or refinance, and taking more of it raises your rate and your monthly payment.
Your next step is to see your own numbers. A participating lender can run every assistance level side by side, so you know exactly what each one does to your payment before you decide.
At Premier Home Team, we'll connect you with lenders who have done this program for our clients and help you decide whether it makes sense for you. When you're ready, talk to our team.
If you're also weighing a home across the state line, here's how first-time buyer programs work in our Pennsylvania counties:
- First-Time Home Buyer Programs in Philadelphia, PA
- First-Time Home Buyer Programs in Delaware County, PA
- First-Time Home Buyer Programs in Montgomery County, PA
- First-Time Home Buyer Programs in Chester County, PA
- First-Time Home Buyer Programs in Bucks County, PA
Robin Martin
Realtor® | Premier Home Team | Keller Williams Empower | PLACE
or another way